What core structural problems does on-chain infrastructure solve?
It can reduce settlement friction, lower bilateral reconciliation overhead, and support a shared verifiable ledger, depending on the asset, participants, and architecture.
Build more programmable, traceable, interoperable, and automated financial systems using distributed ledger technology, audited smart contracts, and institutional asset tokenization.
Atomic models when the context allows
Traceable evidence for authorized participants
Smart contract transfer restrictions
Operations without market close downtime
PARADIGM & FOUNDATIONS
It is a suite of blockchain-based software protocols and distributed systems that execute the registration, custody, transfer, and settlement of financial assets using deterministic code in smart contracts.
Unlike traditional banking silos fragmented across disconnected databases requiring heavy manual bilateral reconciliation, on-chain infrastructure unifies recording and value exchange onto a shared, auditable rail.
The distributed ledger can coordinate shared records and rules, reducing selected manual reconciliation steps without replacing custodians, banks, operators, or legal controls.
Can provide a shared, verifiable record that supports accounting and regulatory audits for authorized participants.
Enables predefined logic for selected schedules, events, transfers, and financial processes.
Open software architecture connecting with core banking, enterprise ERPs, and global payment networks via secure APIs and oracles.
EFFICIENCY COMPARATIVE MODEL
Structural analysis comparing legacy financial market infrastructures with programmable accelerated settlement networks.
| Operational Dimension | Traditional Infrastructure | On-Chain Infrastructure |
|---|---|---|
| Settlement Cycle | Deferred settlement cycles (typically T+2 business days) with accumulated counterparty risk. | Can support atomic or conditional settlement models closer to T+0 depending on the asset, participants, custody, payment rail, and regulation. |
| Accounting Reconciliation | Manual bilateral reconciliation across independent ledgers susceptible to data discrepancies. | Shared records can coordinate transaction and settlement events when system conditions allow. |
| Back-Office Overhead | High administrative burden handling paper records, signature verification, and manual notices. | Algorithmic automation of corporate actions via audited and deterministic smart contracts. |
| Transactional Availability | Restricted to banking hours and business days with international cut-off windows. | Continuous 24/7/365 operations on resilient distributed networks without single points of failure. |
| Cash Flow Programmability | Rigid workflows reliant on human intervention or isolated scripts without guaranteed execution. | Programmable money: automated payments executed conditionally based on cryptographically verified events. |
| Auditability & Traceability | Periodic ex-post forensic audits based on sample testing and delayed reporting. | Verifiable traceability for recorded states and events, without automatically validating external data. |
Nota metodológica: La comparación T+2 frente a modelos próximos a T+0 se presenta como un modelo de capacidades arquitectónicas. La velocidad final depende del activo, payment rail, regulación, custodia, liquidez y participantes del mercado.
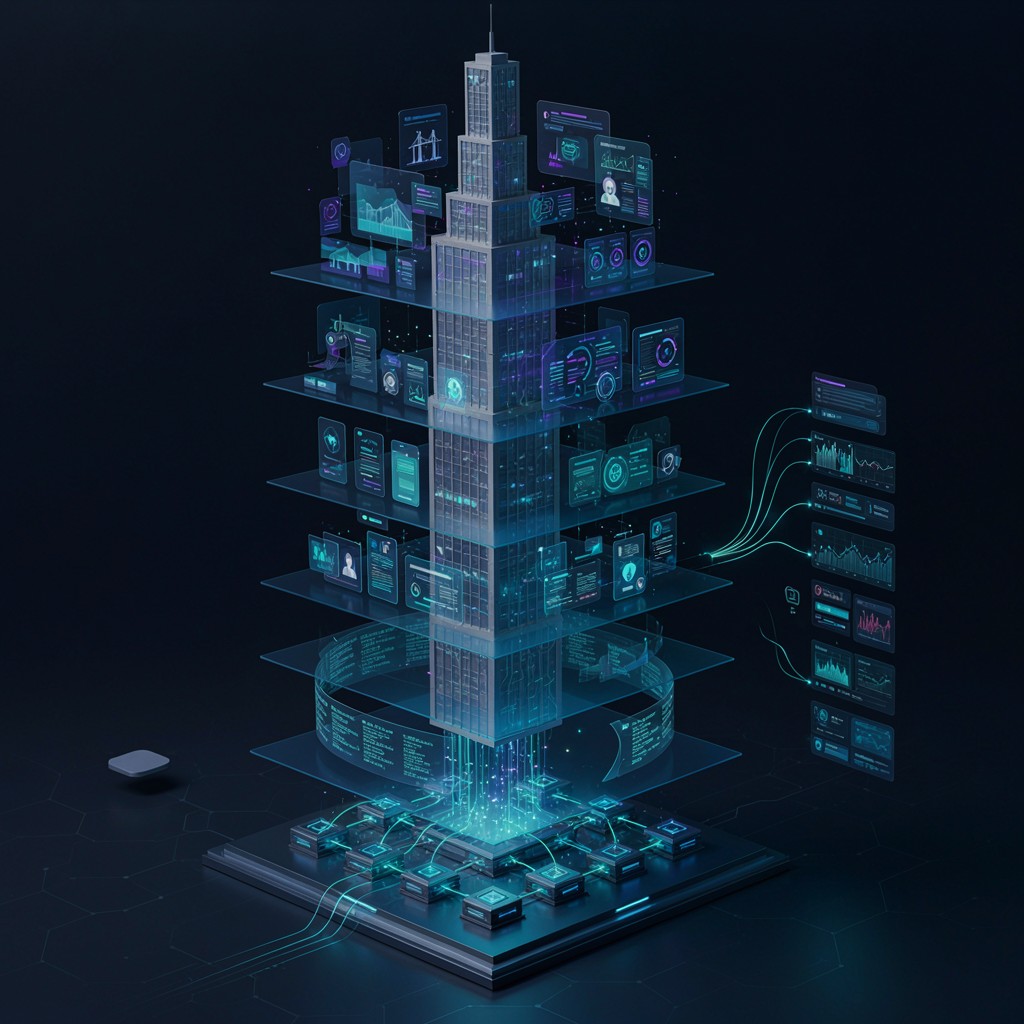
5-LAYER MODULAR ENGINEERING
Decoupled technology stack designed to support resilience, scalability, and programmable compliance within a broader legal and operational framework.
Base blockchain network or DLT maintaining shared states and coordinating transactions according to the custody and operating model.
Standardized framework issuing digital tokens mapped to special purpose legal vehicles (SPVs), managing cap tables, fractional rights, and economic entitlements.
Audited smart contracts orchestrating fund flows, automated dividend dispersion, coupon payouts, and algorithmic corporate governance.
Runtime eligibility enforcement: verifiable digital identity credentials (ONCHAINID) verifying KYC/AML and investor accreditation before allowing token transfers.
Data pipelines feeding market prices, indexing on-chain events, and synchronizing transactions with legacy core banking and enterprise ERP systems.
TRANSACTIONAL LIFECYCLE
End-to-end operational sequence from asset origination to applicable distribution events and settlement.
The real-world or financial asset is structured under a compliant legal vehicle (SPV). Investors complete verifiable digital identity checks and join the approved whitelist.
The tokenization engine mints representative tokens with embedded transfer rules. Digital assets and cash reserves are secured under institutional MPC custody schemes.
Defined economic events can trigger distribution instructions through smart contracts when funds, authorizations, custody, and legal conditions are in place.
STRATEGIC CAPABILITIES
Potential automation for vendor payments, treasury rules, and defined corporate events with operational controls and authorizations.
Granular representation of assets or rights (real estate, debt, funds) with transfers conditioned on legal structure, eligibility, and market infrastructure.
Regulators and auditors can query ledger state directly without waiting for delayed banking statements or complex bilateral reconciliations.
International capital and asset transfers with immediate atomic finality, bypassing the fees and delays of multiple correspondent banking chains.
PRODUCTIVE RWA APPLICATIONS
Enterprise implementations directly connected to our existing technology ecosystem and case studies.
Fractionalization of commercial and residential real estate assets, optimizing capital syndication and automated rent distribution.
Solar generation verification and digital token issuance to fund photovoltaic power plants with transparent cash flows.
Digital LP management, automated capital call workflows, and accelerated settlement for private fund shares.
Smart contracts recording distribution rules and corporate events when the legal, operational, and payment model allows.
INTEGRACIÓN NORMATIVA Y TÉCNICA
La infraestructura financiera on-chain no sustituye el marco jurídico: lo integra en la arquitectura del sistema.
On-chain no significa fuera del sistema jurídico. Un smart contract no equivale automáticamente a un contrato legal. Su relación debe diseñarse coordinando la representación digital de activos, las reglas de transferencia, la identidad y el cumplimiento con la documentación contractual y la regulación aplicable.
Jurisdicción aplicable, regulación vigente y naturaleza del activo representado.
Documentación legal, términos, condiciones y derechos de las partes.
Procesos KYC/KYB, whitelisting y control de acceso.
Lógica programable estructurada para reflejar reglas permitidas.
Restricciones operativas automatizadas según elegibilidad.
Historial inmutable y trazabilidad del ciclo de vida.
Datos verificables para auditores y reguladores.
La tokenización requiere definir qué representa jurídicamente el token y cuáles son los derechos asociados, dependiendo de la jurisdicción.
Las reglas jurídicas y la documentación contractual pueden complementarse con la lógica programable de ejecución automatizada.
El compliance programable facilita controles de KYC/KYB, whitelisting de participantes y restricciones de transferencia on-chain.
Explora cómo estas dimensiones se aplican en la tokenización de activos inmobiliarios o en la energía solar tokenizada.
SECURITY, RISKS & GOVERNANCE
Institutional adoption requires transparent risk engineering across smart contract logic, key management, and securities regulations.
All contracts are developed using battle-tested libraries (OpenZeppelin) and undergo formal verification and third-party security audits to eliminate vulnerabilities.
Multi-party computation (MPC), multi-signature governance, and timelock controllers protect treasury assets and prevent single points of failure.
Decentralized oracle networks with data aggregation across multiple independent providers mitigate price manipulation or stale data risks.
Engineered in strict alignment with securities regulations and data privacy frameworks, binding tokens to legally enforceable off-chain SPVs.
ADOPTION METHODOLOGY
Underlying asset due diligence, SPV legal structuring, compliance rules definition, and optimal blockchain network selection.
Smart contract development, identity verification registries, automated yield models, and comprehensive local test suites.
Connecting with corporate ERP systems, setting up oracle feeds, and configuring fiat/stablecoin payment on-ramps in a controlled staging sandbox.
Independent third-party code audit, production mainnet deployment, investor onboarding, and ongoing technical support.
ONTOLOGICAL SUMMARY
It can reduce settlement friction, lower bilateral reconciliation overhead, and support a shared verifiable ledger, depending on the asset, participants, and architecture.
It focuses on regulated real-world assets (RWA), verified counterparties (KYC/AML), programmatic compliance, and fiat-backed settlement rails without speculative tokenomics.
They provide a modular smart contract suite for permissioned security tokens that can condition transfers on sender and receiver eligibility when the identity and compliance model requires it.
Via event listeners that capture on-chain transactions in real time and trigger authenticated webhooks to REST/GraphQL APIs compatible with SAP, Oracle, or proprietary core systems.
FREQUENTLY ASKED QUESTIONS
Technical, legal, and operational answers about implementing on-chain financial infrastructure.
It is a set of software protocols based on distributed ledger technology (DLT) and blockchain that can record, issue, transfer, and settle financial assets through deterministic smart-contract logic, subject to the relevant asset, participant, and regulatory model.
Traditional systems often coordinate multiple ledgers and reconciliation processes. On-chain infrastructure can provide a shared, auditable transaction rail and support settlement models closer to T+0 when the asset, participants, liquidity, custody, and regulatory framework allow it.
No. It can complement existing institutions, custodians, fund managers, and banking systems. Those participants remain important for issuance, custody, liquidity, legal enforceability, and regulated operations.
Depending on the legal and operational model, real-world assets such as fund interests, real estate rights, receivables, renewable-energy projects, and corporate notes can be represented digitally with defined ownership and transfer conditions.
Smart contracts encode and execute defined business rules, such as eligibility checks, payment schedules, corporate actions, or conditional transfers. They do not replace the legal, operational, or governance controls around those rules.
Identity credentials, claim issuers, transfer restrictions, and compliance services can be combined to check KYC/AML requirements, investor eligibility, and jurisdictional rules before a permitted transfer is executed.
No. Depending on the jurisdiction and operating model, settlement may use regulated stablecoins, tokenized deposits, commercial-bank money, or other approved payment rails. The selected rail determines the remaining liquidity, custody, and counterparty risks.
Integration layers can combine event indexers, signed webhooks, middleware, and REST or GraphQL APIs to synchronize relevant blockchain events with ERP, CRM, accounting, and internal operational systems.
Key risks include smart-contract vulnerabilities, oracle failures, key management, privacy, and operational errors. Mitigations can include independent audits, testing, circuit breakers, redundant data sources, MPC or multisignature custody, and governance controls.
A pilot timeline depends on the asset, regulatory scope, integrations, custody model, and testing requirements. A sandbox pilot may be structured over several weeks, but the estimate should be confirmed after technical and regulatory discovery.
Blockchain provides cryptographic recording, traceability, and automated execution, but it does not inherently guarantee legal security. Legal security is achieved when the on-chain architecture is designed to reflect and comply with the applicable jurisdiction, contractual documentation, and current regulations.
No. A smart contract is programmable logic that automates the execution of certain operational rules and transfers. However, the rights, obligations, legal terms, and dispute resolution mechanisms remain governed by the underlying contractual documentation and applicable legal framework.
Let us discuss how to modernize your capital flows, digital asset issuance, or treasury operations with enterprise-grade blockchain architecture.
Initial technical feasibility session with our senior software architects.